Globex Mining Enterprises Inc. Announces Normal Course Issuer Bid
11. Oktober 2026, 08:48
Triple Flag Announces Strong Revenue in Q3 2026 and First Deliveries from Ravenswood
Share
TORONTO--(BUSINESS WIRE)--Triple Flag Precious Metals Corp. (with its subsidiaries, “Triple Flag” or the “Company”) (TSX: TFPM, NYSE: TFPM) announced revenue of US$106.7 million for the third quarter of 2026 from quarterly metal sales of 25,030 gold equivalent ounces (“GEOs”). All dollar amounts are expressed in US dollars, unless otherwise noted.
“Our business achieved strong performance in the third quarter, including the first quarter of deliveries from the Ravenswood gold mine in Australia. Triple Flag is on track to achieve sales between the midpoint and high end of our recently increased guidance for 2026 of 100,000 to 110,000 GEOs,” commented Sheldon Vanderkooy, CEO.
“We are also pleased to congratulate our operating partners on several accomplishments during the quarter that demonstrate the top-tier quality of our portfolio. At Northparkes, Evolution highlighted that the ongoing mill expansion study will contemplate a higher level of throughput ranging from 10 to 11 Mtpa. Compared to the current mill run-rate of approximately 7.5 Mtpa, the significant growth to be delivered from the 575 million tonne measured and indicated resource base1 at our flagship asset is clear.
Additionally this past month, we saw first gold pour declared ahead of schedule at Koné, as well as commercial production achieved at Johnson Camp Mine. Exploration drilling also returned exceptional grades over long intervals at the Vault Zone of Tamarack, including 46.4 meters at 54.78% CuEq2. The resource upside potential at Tamarack is impressive and we look forward to the release of the project feasibility study in the fourth quarter.”
Preliminary Q3 2026 Results3
GEOs Sold and Revenue by Commodity
Q3 2026
GEOs Sold Revenue ($M)
Gold
16,519 70.4
Silver
7,530 32.1
Copper and other
981 4.2
Total
25,030 106.7
 Alles anzeigen
Danke an Sorgenfrei..., p.s. lt. ceo.ca Forum soll wohl am 12.10. Entscheidung bei CDPR über "weitere Grundstücksrechte" fallen
Fasse nachfolgenden Text auf max. 2 A4 Seiten zusammen und übersetze auf deutsch! Konzentriere dich auf Daten, Fakten, Zahlen!
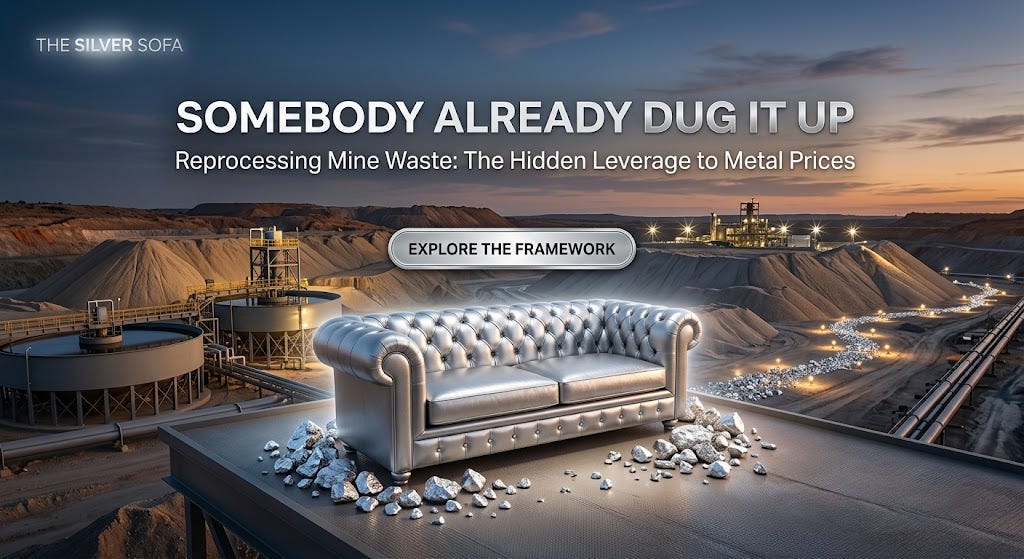
https://silversofa.substack.com/p/somebody-already-dug-it-up
Hier ist die prägnante, auf Daten, Fakten und Zahlen fokussierte deutsche Zusammenfassung des Artikels „Somebody Already Dug It Up“ (The Silver Sofa, September 2026):
Zusammenfassung: Die Ökonomie der Erzanreicherungs- & Taillingerz-Wiederaufbereitung
Die Aufbereitung von Minenabfällen (Tailings) unterscheidet sich grundlegend vom klassischen Bergbau: Es entfallen Bohrungen, Sprengungen, Schwerstransporte und der Schachtbau. Das Material liegt bereits zerkleinert an der Oberfläche.
Der entscheidende Erfolgsfaktor ist nicht der Erzgehalt (Grade), sondern die Eigentums- und Vertragsstruktur um die Abraumhalden („Who owns the dirt?“). Der Artikel analysiert hierzu vier Geschäftsmodelle.
1. Modell Eins: Vollständiges Eigentum an den Abraumhalden
- Beispielunternehmen: DRDGOLD (JSE: DRD / NYSE: DRD) – Gold
- Mineralreserven: 694,5 Millionen Tonnen mit einem extrem niedrigen Goldgehalt von nur 0,29 g/t Gold.
- Finanzkennzahlen: Erwirtschaftete einen Operativen Gewinn von 6,5 Milliarden Südafrikanischen Rand (ZAR).
- Besonderheiten & Vorteile:
- DRDGOLD besitzt das Material sowie das Land darunter zu 100 %.
- Voller Hebel auf den Metallpreis: Steigt der Goldpreis um 100 USD/oz, fließt der operative Gewinnzuwachs nach Abzug der verarbeitungsspezifischen Betriebskosten (OPEX) direkt an das Unternehmen.
- Keine Verpflichtung zur Zahlung von Lizenzgebühren (Royalties) oder Gewinnbeteiligungen an Dritte.
2. Modell Zwei: Langfristige Pacht & Lizenzgebühren (Toll Processing)
- Beispielunternehmen: Amerigo Resources (TSX: ARG) – Kupfer & Molybdän
- Betriebsmodell: Verarbeitet frische und historische Abraumhalden (Tailings) der riesigen El Teniente-Mine von Codelco in Chile.
- Vertragslaufzeit & Konditionen:
- Vertrag läuft bis mindestens 2037.
- Gleitende Lizenzgebühr (Sliding Scale Royalty
An Codelco wird eine Lizenzgebühr gezahlt, die mit steigendem Kupferpreis exponentiell ansteigt.
- Auswirkungen auf die Hebelwirkung:
- Bei niedrigen Kupferpreisen profitiert Amerigo von geschützten Margen.
- Bei sehr hohen Kupferpreisen schöpft Codelco über die gleitende Skala einen Großteil der Extra-Gewinne ab. Das Unternehmen wirkt finanziell eher wie eine Mautstraße (Toll Road) mit gedeckeltem Aufwärtspotenzial.
3. Modell Drei: Service-Betreiber ohne Eigentum an Rohstoffen
- Beispielunternehmen: Jubilee Metals Group (LSE: JLP) – Chrom, PGM & Kupfer
- Betriebsmodell: Entwickelt Aufbereitungstechnologien und betreibt Verarbeitungsanlagen für Dritte in Südafrika und Sambia.
- Vertragsstruktur:
- Jubilee besitzt die Abraumhalden in der Regel nicht selbst, sondern schließt Dienstleistungs- und Aufteilungsverträge ab.
- Vor- und Nachteile:
- Niedriges Kapitalrisiko: Sehr geringe Vorab-Investitionskosten für den Erwerb von Vorkommen.
- Eingeschränkter Metallpreis-Hebel: Verträge haben oft vertragliche Obergrenzen oder Festgebühren. Bei einem Rohstoff-Boom profitiert primär der Eigentümer der Halde, nicht der Anlagenbetreiber.
4. Modell Vier: Integrierter Eigenabbau mit historischer Wiederaufbereitung
- Beispielunternehmen: Pan American Silver (TSX: PAAS / NYSE: PAAS) – Silber (Beispiel: Manantial Espejo / Agua de la Falda)
- Betriebsmodell: Die Wiederaufbereitung von Abraumhalden dient als Ergänzung oder Überbrückung für bestehende eigene Minen- und Mühleninfrastrukturen.
- Effekte:
- Bietet hohe operative Flexibilität und verlängert die Lebensdauer teurer Aufbereitungsanlagen ohne neue Abbau-Kapitalausgaben (CAPEX).
Kern-Erkenntnisse & Kennzahlen im Vergleich
Model 1 (DRD) 100 % Eigentum Maximal (100 %) Sehr niedrige Erzgehalte (z. B. 0,29 g/t Au) Model 2 (Amerigo) Pacht / Vertrag (bis 2037) Gedeckelt (durch Sliding-Scale Royalty) Exponentiell steigende Abgaben bei Preisanstiegen Model 3 (Jubilee) Kein Eigentum (Dienstleister) Gering / Moderat Vertragsverlängerungen & Gegenparteien-Risiko Model 4 (PAAS) Eigentum im Rahmen der Mine Hoch (fokussiert auf Infrastruktur) Endliche Abraumreserven vor Ort Fazit des Artikels:
Die reine Wiederaufbereitung von Minenabfällen ist finanztechnisch erstklassig, da Abbau- und Zerkleinerungskosten entfallen. Wer jedoch den vollen finanziellen Hebel auf steigende Metallpreise sucht, muss gezielt Unternehmen wählen, die das Material selbst besitzen (Modell 1 wie DRDGOLD) und nicht lediglich als Pächter oder Dienstleister agieren.
Sehr schön, danke! Nur deine KI war sehr kreativ. Modell 2 im Text war eigentlich Andean Precious Metals und Modell 4 handelte von Cerro de Pasco. Daher habe ich den Artikel auch hier eingestellt.
Grüße 
https://www.mining.com/panama-commission-urges-orderly-closure-of-first-quantums-cobre-mine/
DENVER, CO / ACCESS Newswire / September 28, 2026 / Vox Royalty Corp. (NASDAQ:VOXR)(TSX:VOXR) ("Vox" or the "Company"), a returns-focused mining royalty and streaming company, is pleased to announce that its subsidiary, Vox Royalty Australia Pty Ltd. ("Vox Australia"), has entered into a binding agreement to acquire an effective 0.75% net smelter return royalty (the "Royalty") over the construction-stage Sorby Hills silver-lead project in Western Australia ("Sorby Hills" or the "Project"), for total cash consideration of $13,000,000 from a private seller (the "Transaction").
The Transaction remains subject to the completion of conditions precedent customary for a royalty transaction of this nature and Foreign Investment Review Board approval in Australia and is expected to complete in the fourth quarter of 2026. Sorby Hills is 100% owned and operated by Boab Metals Limited ("Boab Metals"), an Australian ASX-listed company.
Kyle Floyd, Chief Executive Officer of Vox, stated: "We are excited to add near-term silver dominant revenue to the Vox portfolio through an uncapped royalty over Sorby Hills, which is on track to become one of Australia's largest silver mines. Sorby Hills is fully permitted, fully funded and under construction, with Boab Metals targeting first concentrate production in the second half of 2027 and average annual production of ~2.2Moz of silver and 68kt of lead over an initial 8.5-year mine life. We look forward to the upcoming results of the 2026 reserve extension drilling program and its potential mine life implications. Acquiring a construction-stage royalty within 12-months of first production is precisely the profile we target at Vox: near-term, precious metals revenue, with significant optionality."
Key Points
https://www.cnbc.com/2026/09/28/northern-star-shares-gold-fields-takeover-bid.html
Maiden PEA outlines a 9.4-year, 12,000 tonne per day open pit operation producing an average of 188,000 ounces of gold per year (223,000 ounces per year over the first five years) at a US$3,600/oz gold price
After-Tax NPV increases to C$3 Billion and 57% IRR at US$4,500/oz gold price
PEA Highlights
All amounts in Canadian dollars unless otherwise noted. Base case gold price of US$3,600/oz (flat) and an exchange rate of US$0.72 = $1.00.
Cabaçal DFS's Highlights:
(All amounts are in United States Dollars unless otherwise stated)
| Cabaçal DFS After-Tax outputs | Base Case Economics $3,570 Au / $5.03 Cu / $50.17 Ag | Spot Price Economics* $4,394 Au / $6.53 Cu / $64.14 Ag |
| Net Present Value @ 5% | USD 2.092 Billion | USD 2.902 Billion |
| Internal Rate of Return | 107.6.% | 134.7% |
| Payback Period | 0.9 Year | 0.7 Year |
| NPV5/Capex | 6.5x | 9.0x |
| *Spot metal prices dated on London close, 10 September 2026 | ||
- Average annual production of 183,526 AuEq;
- AISC of USD 715/oz AuEq;
- Average annual after-tax free cashflow of USD 413.8 million;
- Installation Licence for power line construction granted.
Empress Announces Agreement to Acquire Tongon Gold Stream and Secures Debt Financing
VANCOUVER, B.C. - September 17, 2026 - Empress Royalty Corp. (TSXV: EMPR | OTCQX: EMPYF) ('Empress' or the 'Company') is pleased to announce its wholly-owned subsidiary, Empress Royalty Holding Corp. ('Empress Holding s ') entered into a Stream Purchase Agreement (the 'SPA') today with Appian Tongon Streamco Ltd. (the 'Seller', 'Appian' ) to acquire its interest in the gold s tream (the 'Stream') on the Tongon Gold Mine ('Tongon') in Côte d'Ivoire , owned and operated by the Atlantic Group, for an upfront cash payment of US$62M (the ' Investment ').
In addition, Empress Holdings, as the Borrower, entered into a US$75M senior secured, credit facility (the ' Credit Facility') today with Appian Empire Loanco Ltd. (the 'Lender', 'Appian' ). The Credit Facility provides for an initial draw of US$55M at closing to partially fund the Investment and a further US$20M commitment to fund future royalty and stream acquisitions. The balance of the Investment and closing costs will be funded from Empress' existing cash resources.
'This will be a transformational transaction for Empress,' stated Alexandra Woodyer Sherron, CEO and President of Empress. ' The Tongon Gold Stream is expected to substantially increase our gold ounces, revenue and cash flow from an established producing mine. Additionally, our due diligence has identified significant opportunity for continued reserve replacement and successful exploration providing additional long-term value to Empress. The US$75M credit facility provides Empress with the financial capacity to complete this Investment while preserving our liquidity and limiting shareholder dilution. It also provides additional capital to pursue future royalty and stream opportunities as we continue to build scale and quality of the Empress portfolio.'
https://www.newsfilecorp.com/r…yalty-and-Streaming-Model
Neuer Anlauf Mr. Watson und Co.? Haben ja schon genug billige shares eingesammelt.
Die Verwässerung geht schon vor dem Börsengang munter weiter...