Triple Flag: A Solid Buy-The-Dip Candidate
https://seekingalpha.com/article/4812696-triple-flag-a-solid-buy-the-dip-candidate
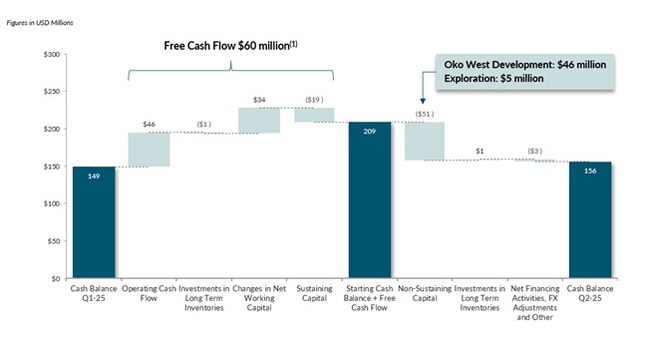
- Triple Flag delivered record Q2'25 results, with GEO sales up 6% and strong revenue/cash flow growth despite some minor setbacks that softened its deliveries.
- Despite these setbacks, it remains on track to meet 2025 guidance, demonstrating the business' resilience from a highly diversified portfolio focused on top-ranked jurisdictions.
- Triple Flag has paused buybacks, unlike some peers unloading on buybacks at far less attractive valuations, highlighting its discipline to be opportunistic.
- In this update, we'll dig into its Q2'25 results, some recent developments, and why it continues to be one of the best ways to get exposure to precious metals.
Summary
Triple Flag had another record quarter in Q2'25, and more records are on deck in H2'25. This is related to contributions from new assets (Arcata, Tres Quebradas, Johnson Camp), higher silver prices, new records in gold prices, and the fact that it continues to have a heavy silver weighting relative to its peers in a favorable period of recent silver price outperformance.
Unfortunately, this heavy silver weighting will see a minor hit next year with the step down on its Cerro Lindo stream in Peru, but this is hardly a deal-breaker for the investment thesis, and Triple Flag's deep portfolio can easily withstand this impact, as it did the sharp drop in grades vs. peak years at Fosterville.
Meanwhile, from a big picture standpoint, Triple Flag may be getting closer to being fairly priced after an impressive two years of share price outperformance vs. gold, but assuming ~150,000 GEOs in 2030 and a 25x free cash flow multiple (greater scale, Tier-1 premium), this is a company that could be trading at ~$40.50/share ($3,100/oz gold price), ~US$45.00/share ($3,400/oz gold price), or ~US$48.80/share ($3,700/oz gold price) using different gold price scenarios and a static $36.00/oz silver price.
Importantly, these fair value estimates exclude over $1.0 billion [US$5.00/share] in net cash (year-end 2030) from ongoing cash build assuming the company does only smaller transactions and no major transactions and simply pays out regular dividends, based on a flat $3,000/oz gold price assumption.
Hence, I see considerable long-term upside for the stock, and I see TFPM as one of the sector's best buy-the-dip candidates for those looking for no-nonsense exposure to gold/silver in a sleep-well-at-night vehicle with a team that has a proven track record of creating shareholder value. In summary, I would view any sharp pullbacks in the stock as buying opportunities, and I would not be surprised to see the stock trading above US$32.00/share by the end of 2026.